How Aerospace and Defense Can Overcome the Big Challenges of Vertical Supply Chain Integration
The Aerospace and Defense Industry is facing a reality it can no longer ignore: the most advanced aircraft, missiles, satellites, drones, and defense systems in the world are only as strong as the supply chains behind them.
For decades, aerospace and defense companies built global supplier networks designed for efficiency, specialization, and cost control. OEMs and prime contractors focused on design, integration, program management, and final assembly, while thousands of suppliers handled everything from forgings and castings to electronics, propulsion components, software, sensors, fasteners, and specialty materials.
That model worked when the world was more stable.
Today, it is under stress.
Defense demand is rising. Commercial aerospace production is trying to ramp up. Missile inventories need replenishment. Space systems are becoming more strategically important. At the same time, suppliers are facing labor shortages, inflation, raw material constraints, cyber risk, geopolitical instability, and limited production capacity.
The result is a new strategic question: should aerospace and defense companies vertically integrate more of their supply chains?
The answer is yes—but carefully.
Vertical integration does not mean owning everything. It means gaining control over the parts of the supply chain that are too critical to fail.
The New Reality: A Single Weak Link Can Stop the Mission
Aerospace and defense products are among the most complex systems ever built. A modern aircraft, missile system, or satellite may depend on thousands of parts from hundreds or even thousands of suppliers. One missing casting, one delayed chip, one unavailable forging, one failed supplier, or one unqualified special process can delay an entire program.
That is the danger of today’s supply chain: the weakest link is often hidden.
Many OEMs have good visibility into their Tier 1 suppliers. But the real bottleneck may be deeper—in Tier 2, Tier 3, or Tier 4. It may be a small machining company, a specialty heat-treat provider, a rare material supplier, a foundry, or a producer of electronic components that few executives have ever visited.
When that supplier fails, the impact moves upward fast.
This is why vertical integration is becoming attractive again. Companies want more control, more visibility, more resilience, and more certainty. But vertical integration is not a magic solution. Bringing work in-house can reduce some risks while creating others: higher capital cost, workforce pressure, operational complexity, supplier tension, and reduced flexibility.
The industry must therefore move from a simple outsourcing mindset to a strategic control mindset.
The question should not be, “Should we make or buy?”
The better question is, “What must we control to protect the mission?”
Real Example: Safran and the Power of Controlling Critical Processes
Safran offers a strong example of strategic vertical integration in action.
In 2026, Safran announced a major investment in its Gennevilliers site near Paris, including a 30,000-ton hydraulic press to strengthen its forging capability. The company said the investment would support strategic parts for commercial and military aircraft engines and help increase output by 2029.
This is not just a factory upgrade. It is a strategic supply chain move.
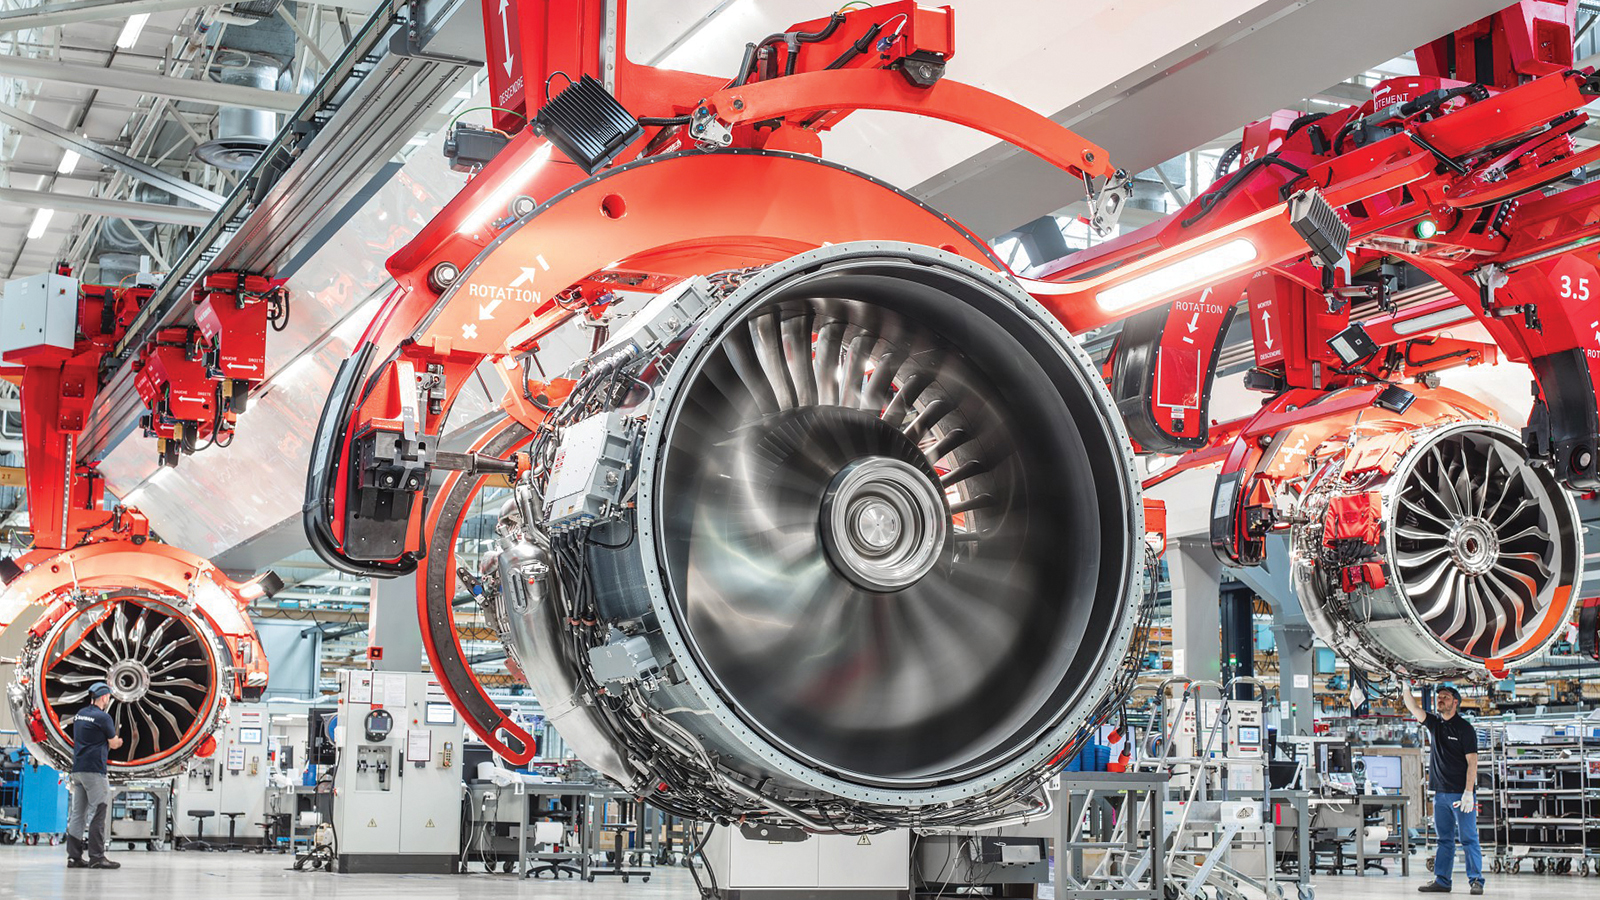
Forgings are not ordinary parts. In aircraft engines, they are often mission-critical components exposed to extreme stress, heat, and performance requirements. If forging capacity becomes constrained, engine production slows. If engine production slows, aircraft deliveries suffer.
Safran’s investment shows a key principle: vertical integration makes the most sense when the capability is technically difficult, strategically important, capacity-constrained, and essential to long-term competitiveness.
Safran is not trying to own every part of the supply chain. It is strengthening control over a bottleneck capability that directly affects engine production, resilience, and national industrial capacity.
That is smart vertical integration.
Real Example: Lockheed Martin and Missile Production Capacity
Lockheed Martin provides another example from the defense side.
In 2026, the company began construction of a new munitions production facility in Troy, Alabama, to support systems such as THAAD interceptors and Next Generation Interceptor production. The move is part of a broader effort to expand missile production capacity at a time when U.S. and allied defense demand is increasing.
This example highlights another reason vertical integration matters: surge capacity.
Defense supply chains cannot be designed only for peacetime efficiency. They must also support crisis response, replenishment, and deterrence. If demand suddenly increases, the supply chain must be able to respond.
Missile production depends on complex networks of propulsion suppliers, electronics providers, energetics manufacturers, precision machining companies, test systems, guidance components, and specialized materials. If any of these areas lacks capacity, production cannot scale.
Lockheed Martin’s expansion shows that vertical integration is not always about acquiring suppliers. Sometimes it is about building internal capacity, modernizing facilities, securing production lines, and aligning investment with long-term government demand.
In defense, capacity is not just a business issue. It is a national security issue.
How the Industry Can Overcome These Challenges
The aerospace and defense industry needs a practical playbook.
First, companies should map their real supply chains. Not just Tier 1 suppliers. Not just contracted suppliers. They need visibility into lower-tier suppliers, critical materials, special processes, and capacity constraints.
Second, they should identify strategic bottlenecks. These are the components, processes, technologies, and materials that can stop a program if they fail.
Third, they should choose the right control model. Some capabilities should be owned. Some should be supported through long-term partnerships. Some should be dual-sourced. Some should be protected through inventory, capacity reservations, or government-backed investment.
Fourth, they should invest in supplier development. Many suppliers do not need to be replaced; they need help becoming stronger.
Fifth, companies should align engineering and supply chain decisions earlier. A design that depends on one rare material, one fragile supplier, or one unproven process creates risk before production even begins.
Sixth, government and industry must work together. Defense suppliers need stable demand signals, multiyear procurement, faster contracting, and targeted investment in critical industrial base capabilities. Suppliers cannot justify major capital investment if future demand is uncertain.
Finally, vertical integration must become a board-level issue. It affects strategy, production, finance, quality, cybersecurity, national security, and customer trust. It is too important to be treated as a purchasing project.
The Leadership Shift: From Cost Control to Mission Control
For years, supply chain was often viewed as a cost center. That mindset is outdated.
In aerospace and defense, supply chain capability is now a strategic advantage. The companies that can secure capacity, protect critical materials, develop suppliers, and scale production faster will outperform those that only chase lowest price.
The industry must stop asking only, “Who can make this cheaper?”
It must also ask, “Who can help us deliver reliably, securely, and at scale?”
That shift changes everything.
Safran’s investment in forging capacity shows how controlling a critical process can strengthen resilience. Lockheed Martin’s missile production expansion shows how capacity investment can support national defense needs. These examples point to the future: the winners will be the companies that understand where control matters most and act before the bottleneck becomes a crisis.
Conclusion: Control the Chain Before the Chain Controls You
Vertical supply chain integration is not about owning everything. It is about protecting what matters most.
The aerospace and defense industry should integrate selectively, invest strategically, and partner intelligently. It should own the capabilities that are too critical to fail, develop suppliers that are too important to lose, and digitally monitor the deeper tiers that are too risky to ignore.
The next generation of aerospace and defense competition will not be won only by the best designs. It will be won by the companies that can actually deliver those designs—on time, at scale, and with confidence.
In this industry, supply chain resilience is no longer a back-office function.
It is mission readiness.
It is competitive advantage.
And in many cases, it is national security.
By Azita Hajihassani, Ph.D., MBA